Banker's Digest
2026.09
Lessons from Korea's stock market surge and circuit breakers
Chen Szu-Jui


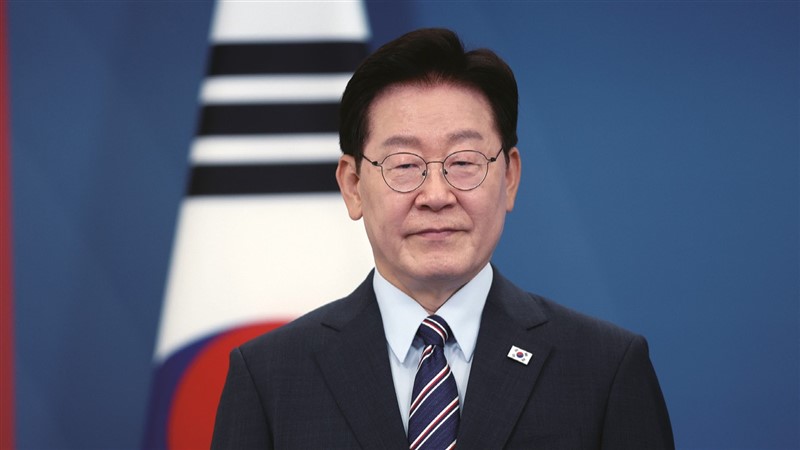
South Korea has been the world’s best-performing stock market in 2026. By the end of July, the KOSPI had reached 6,595.45, up 56.5% from the end of 2025, slightly outperforming Taiwan’s 48.9% gain. Yet compared with its mid-June peak of 9,114.55, the index plunged 27.6% in just over a month, inflicting heavy losses. Several factors drove the rally: President Lee Jae Myung’s determined push for corporate governance reform, soaring demand for memory chips and AI storage, foreign investors reducing their exposure to Hong Kong and Japanese equities while increasing allocations to Korea, and a large numbers of retail investors re-entering the market. It was the same forces behind the boom which also contributed to the reversal. Equity valuations rose to historic highs, while shares in memory-chip giants Samsung Electronics and SK hynix corrected after steep gains. The escalating conflict between the US and Iran drove oil prices higher and intensified inflation concerns. Single-stock leveraged and inverse ETFs amplified gains and losses, producing extreme volatility. Circuit breakers were triggered nine times during the year, prompting regulators to introduce emergency restrictions on leveraged ETFs. Lee’s determination to reform the market is rooted partly in his personal experience. Early in his career, he turned to day trading to supplement his income, but ultimately suffered substantial losses. The experience convinced him that the stock market was structurally unfair: controlling shareholders of large conglomerates could enrich themselves through transactions that harmed minority shareholders, while ordinary investors were disadvantaged by information asymmetry and institutional weaknesses. During the presidential campaign, Lee purchased KRW40 million, or approximately US$27,600, in Korean index ETFs, and pledged to invest another KRW1 million each month for the following five years if elected. After taking office in June 2025, he launched an ambitious “KOSPI 5000” initiative aimed at eliminating the longstanding “Korea discount” that had depressed domestic equity valuations. To improve corporate governance, Lee drew inspiration from former Japanese Prime Minister Shinzo Abe’s efforts to increase transparency on the boards of listed companies, while pursuing a Wall Street-style model of board accountability. Listed companies were required to strengthen the role of independent directors and given time to comply, with those failing to meet the standards potentially facing exclusion from the main board. He also tightened shareholder protections. Treasury shares newly acquired by listed companies from 2025 onward were required to be retired within one year, while existing treasury shares had to be retired within 18 months. Amendments to Korea’s Commercial Act, broadly comparable to Taiwan’s Company Act, limited the voting rights of the largest shareholder and related parties in independent-director elections to 3%. Alongside these corporate governance measures, Lee offered incentives to support the equity market. The securities transaction tax was cut from 0.3% to 0.1%, while tax incentives encouraged companies to increase dividend payments. The government also prohibited short selling, eased foreign-investor access and removed foreign shareholding limits. To reduce the risk of large investors exploiting retail traders, restrictions were imposed on high-frequency quantitative trading: trading would be suspended for five minutes if prices moved by more than 5%. These incentives, combined with the returns by Korean corporates from the AI boom, drove the market up by more than 100% in just over a year. The rally attracted substantial foreign capital and pushed the number of securities accounts in Korea to 100 million – nearly twice the country’s 2025 population of 51.892 million. Roughly one-third of the population participated in trading, while margin transactions accounted for 35% of activity, surpassing the leverage peak reached during the 2015 bull market. The market boom allowed the KOSPI to surpass Lee’s 5,000-point target with ease. It also began changing how Korean households viewed wealth creation. Real estate had long been regarded as virtually the only path to prosperity, accounting for nearly three-quarters of household assets. Soaring apartment prices, however, also left Korean households carrying one of the world’s highest debt burdens. Lee’s image as a president who understood retail investors, together with his willingness to confront the country’s powerful conglomerates, helped lift his approval rating to a high of 61%. A rising tide, however, can just as easily turn. The extraordinary bull market made retail investors increasingly complacent. On May 27, 2026, Korea authorized 2x-leveraged ETFs tracking individual stocks such as Samsung Electronics and SK hynix, and investors rushed in. According to the Korea Exchange, 18 leveraged and inverse products linked to Samsung Electronics and SK hynix were listed, with total assets exceeding KRW14 trillion, or approximately US$9.8 billion. Retail investors held 92%. When both names came under selling pressure due to elevated valuations, retail investors once again bore the brunt of the losses. The irony was striking for a president who had positioned himself as a champion of retail shareholders. Meanwhile, the market-wide circuit-breaker and sidecar mechanisms designed to protect retail investors proved less effective than intended. The two companies together accounted for nearly half of the KOSPI’s weighting. Combined with rapid movements in global capital and leveraged trading, this degree of concentration magnified volatility and triggered margin calls and cascading sell-offs, leaving retail investors with few avenues of escape. Measures intended to attract overseas capital succeeded in lifting foreign ownership of Korean equities above 30%, but global capital is highly sensitive and can exit rapidly in response to policy changes or geopolitical shocks. Similarly, policies intended to encourage retail participation ultimately induced investors to chase momentum. Leveraged ETFs and leveraged single-stock positions magnified market swings, undermining the long-term stability of the market they had been intended to strengthen. The author is a senior financial professional specializing in financial and economic policy analysis.